The 21 Overhead Categories Contractors Should Track
Overhead is every business cost recovered through your markup instead of charged to a job. Sort your expenses into the right buckets and your markup means something; classify them inconsistently and the markup quietly stops covering the business.
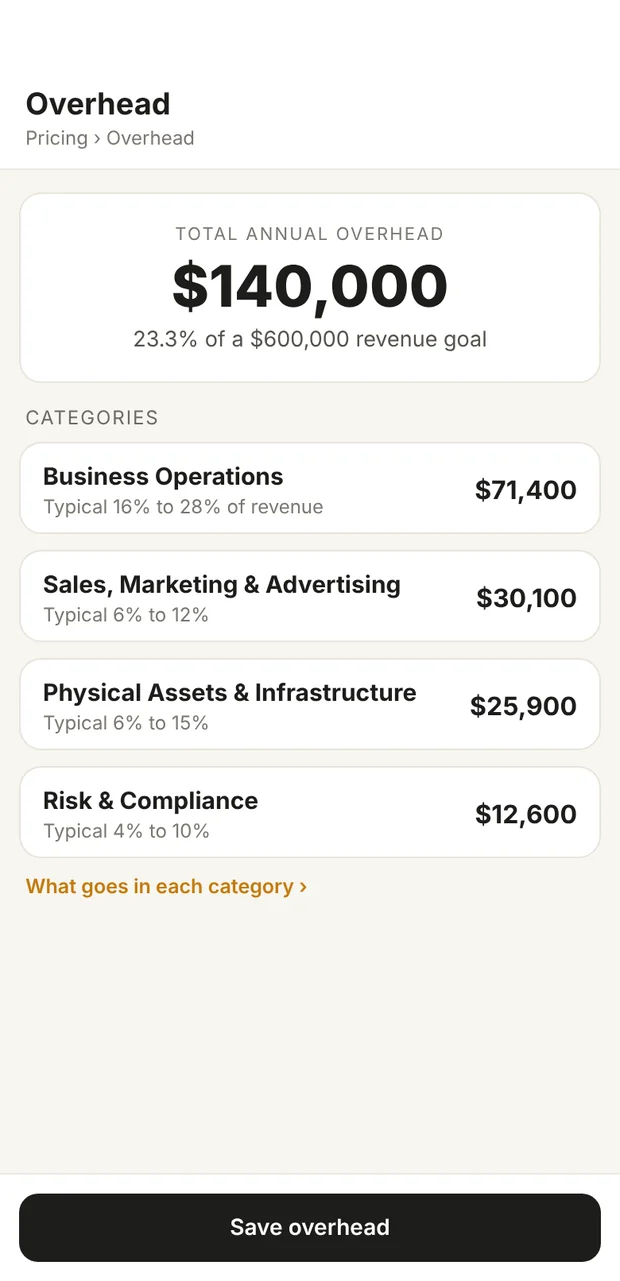
Four categories, one total
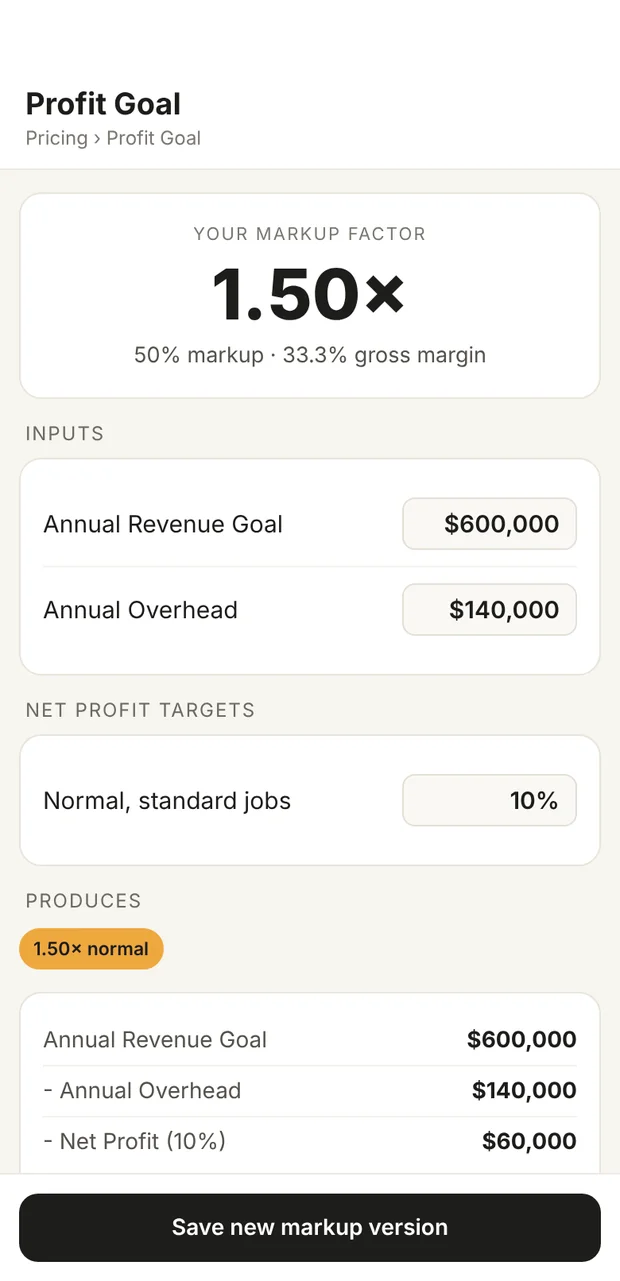
What the total produces
Overhead in Clamp: four categories adding to the year's total, and the Profit Goal markup that total produces against a revenue goal and a profit target. Illustration of the Clamp app.
The rule that actually governs
A job cost is a cost your company consistently assigns to producing a specific job. Overhead is a business cost recovered through your markup instead. Reasonable companies can classify the same expense differently; what none of them can survive is inconsistency. Every cost must be recovered exactly once: in the estimate, or in the markup. Never omitted, never counted twice.
A useful first-pass question: would I still incur this expense without this particular job? If yes, it is probably overhead. But some costs are legitimately a company-specific call, and for those, consistency between your estimates and your markup matters more than the label.
Your markup is only as good as your ability to predict overhead and job costs consistently. The categories below are the buckets that make the prediction consistent. Build your own overhead in them instead of borrowing someone else's percentage.
Worked example
Overhead sets your markup directly. With overhead and profit as shares of revenue, the markup multiplier is 1 / (1 - overhead - profit). Take a shop with a $500,000 revenue goal and $120,000 of true overhead, targeting 10% net profit.
5x8 bathroom remodel, fully itemized →
Inputs
- True overhead: $120,000 on a $500,000 revenue goal, 24% of revenue
- Net profit target: 10% of revenue
- Markup multiplier: 1 / (1 - overhead - profit)
Actions
- With honest books: 1 / (1 - 0.24 - 0.10) = 1 / 0.66 = 1.52x, a 51.5% markup
- Now suppose you decide $30,000 of that overhead, some supervision here, some selling expense there, really belongs in job costs. That can be a legitimate call. Reclassifying is fine when the dollars land consistently in every applicable estimate: a lower markup applied to a larger job-cost base can recover the same money
- The disaster is doing half the move. The $30,000 leaves the overhead budget, so the multiplier falls to 1 / (1 - 0.18 - 0.10) = 1 / 0.72 = 1.39x, a 38.9% markup. But the expense never gets added to any estimate. Now it is recovered nowhere
- On the published 5x8 bathroom estimate with a direct job cost of $13,858.38: priced at the required 51.5% markup, the job sells for $20,997.55. Priced at the half-moved 38.9% against the same unchanged job cost, it sells for $19,247.75
- The omission gives away $1,749.80 on this one bathroom, and every job that year makes the same donation
Reclassification is a choice; omission is a leak. Whatever you call a cost, it must show up exactly once, in the estimate or in the markup, and a half-move recovers it nowhere.
All 21 categories at a glance
The ranges below are Clamp planning defaults: working guardrails from residential contracting and teaching experience, shipped in Clamp's overhead builder and grouped the same four ways. They are not industry averages and not benchmarks. Do not build your markup from somebody else's percentages; enter your actual costs wherever you have them, and use the ranges to sanity-check what you might be forgetting. These are pricing and cash-planning categories, not Schedule C deduction lines. One planning category can require several tax classifications, and some funding requirements are not deductible expenses at all. The clearest case is your own pay: Schedule C's cost-of-labor line says not to include amounts paid to yourself, while this budget must carry it. These ranges apply only when the function exists at your company. Do not total all 21 minimums. Pick the functions your business actually has, enter your real annual dollars, and compare your total with the figures for your type of work below.
| Category | Typical range |
|---|---|
| Business Operations | |
| Owner Salary (non-field labor) | 6-10% |
| Office / Administrative Wages | 3-6% |
| Project Management (multi-job PMs) | 2-5% |
| Estimating Department (multi-job) | 1-3% |
| Design Department (multi-job) | 2-6% |
| Accounting & Bookkeeping | 1-2% |
| Financial Reporting / Controller / CFO | 0.5-2% |
| Core Software (accounting, CRM) | 1-2% |
| Training & Development | 0.5-2% |
| Sales, Marketing & Advertising | |
| Sales Department (base pay only) | 2-4% |
| Marketing & Advertising | 3-7% |
| Website & Digital Presence | 0.5-1.5% |
| Physical Assets & Infrastructure | |
| Rent & Utilities | 2-4% |
| Showroom / Warehouse | 2-6% |
| Vehicles & Fuel | 2-4% |
| Tools & Equipment (non job specific) | 1-3% |
| Risk & Compliance | |
| Insurance & Bonding (GL, auto, umbrella) | 2-4% |
| General Warranty Program | 0.5-2% |
| Business Licenses & Compliance | 0.2-1% |
| Operating Capital Reserve Account | 1-3% |
| Financing & Bank Fees | 0.5-2% |
The categories
Every expense gets one primary home, or you will count it twice. The rule used here and in Clamp's builder: department categories hold both department labor and department-specific tools, while shared systems used across the business sit in Core Software. A subscription appears in one category only. So shared software sits in Core Software, all training in Training & Development, all company insurance in Insurance & Bonding, all vehicle costs in Vehicles & Fuel, regardless of which department uses them.
Tap a category for what belongs in it, what does not, and the mistake to avoid.
Owner Salary (non-field labor)6-10%tap for details⌄Compensate the owner for leadership, management, and business operations.
Office / Administrative Wages3-6%tap for details⌄Covers the administrative infrastructure required to run the company.
Project Management (multi-job PMs)2-5%tap for details⌄Overhead cost of managing production across jobs.
Estimating Department (multi-job)1-3%tap for details⌄Cost of producing estimates and preconstruction planning.
Design Department (multi-job)2-6%tap for details⌄Overhead cost of running a design-first operation.
Accounting & Bookkeeping1-2%tap for details⌄Keeping the books accurate and the payroll running.
Financial Reporting / Controller / CFO0.5-2%tap for details⌄Financial visibility beyond bookkeeping: budgets, job-cost review, cash forecasting.
Core Software (accounting, CRM)1-2%tap for details⌄Business-wide technology systems.
Training & Development0.5-2%tap for details⌄Skill development to improve job performance and efficiency.
Every category here is pre-built in Clamp's overhead tracker, ranges included.
Track yours →Sales Department (base pay only)2-4%tap for details⌄Overhead cost of running your sales system.
Marketing & Advertising3-7%tap for details⌄Lead generation and brand awareness.
Website & Digital Presence0.5-1.5%tap for details⌄Your findability and digital storefront.
Rent & Utilities2-4%tap for details⌄Overhead for office, showroom, or warehouse facilities.
Showroom / Warehouse2-6%tap for details⌄Facility-related expenses supporting production.
Vehicles & Fuel2-4%tap for details⌄Company vehicles used for management, sales, admin, and supervision.
Tools & Equipment (non job specific)1-3%tap for details⌄Non-job-specific tools used across multiple projects.
Insurance & Bonding (GL, auto, umbrella)2-4%tap for details⌄General protection for the business.
General Warranty Program0.5-2%tap for details⌄Systemic warranty obligations across all projects.
Business Licenses & Compliance0.2-1%tap for details⌄Legal permission to operate.
Operating Capital Reserve Account1-3%tap for details⌄Cash reserve equal to 5 to 7 months of overhead.
Financing & Bank Fees0.5-2%tap for details⌄Costs of banking, borrowing, and merchant processing.
Anything that fits none of these buckets gets its own named line item, not a dumping ground. An expense you cannot name is an expense you cannot predict, and unpredicted overhead is how markups end up wrong.
Overhead by type of contractor
Overhead depends more on the kind of work you do than on how big you are. A home builder spreads one office across a few large contracts; a remodeler carries sales, design and estimating for many small ones. Two published references, side by side: a cost-of-doing-business survey from the National Association of Home Builders (NAHB), and the contractor pricing book Markup & Profit: A Contractor's Guide.
Two terms used below. Gross margin is gross profit as a share of revenue: what is left after job costs, before overhead. Net profit is what is left after job costs and overhead. Every "profit" on this page means net profit.
| Type of contractor | What firms report (NAHB survey) | Planning range from Markup & Profit |
|---|---|---|
| Remodeler | 23.6% overhead (average revenue $2.7M; gross margin 29.9%, net profit 6.3%) | 26-34% overhead (gross margin 34-42%+, less 8% net profit). The book's worked example: 28% |
| Specialty trade | No comparable published figure | 21-26% overhead (gross margin 29-34%+, less 8% net profit) |
| New home builder | 12.0% overhead (average revenue $11.3M; gross margin 20.7%, net profit 8.7%) | 13-21% overhead (gross margin 21-29%+, less 8% net profit) |
The NAHB remodeler figure includes indirect construction costs. The builder figure does not.
Survey figures are averages across the firms that responded, with owner pay included. Markup & Profit publishes gross margin ranges, which it defines as overhead plus net profit; the planning range here subtracts the 8% net profit the book uses as a minimum target. The book's markup guidance of 1.50 to 1.70+ for remodeling converts to 33.3% to 41.2%+, close to but not exactly its published 34% to 42%+.
The three profiles Clamp uses
Clamp's free estimate, its published cost pages and its app use the same three illustrative profiles. Each assumes 10% net profit, so the overhead share follows from the markup:
| Profile | Markup | Overhead | Net profit | Gross margin |
|---|---|---|---|---|
| Lean | 30% (1.30x) | 13.1% | 10% | 23.1% |
| Standard | 50% (1.50x) | 23.3% | 10% | 33.3% |
| Full-Service | 100% (2.00x) | 40.0% | 10% | 50.0% |
Standard sits almost exactly on the NAHB average remodeler. Full-Service is above the top of the book's published range: it reflects remodelers with in-house design, sales and project management who price at twice job cost, from Clamp's own practitioner experience rather than a survey. Lean fits an owner whose own pay is carried in job cost. An owner who carries it in overhead runs higher, as the $100,000 solo contractor guide shows at 36.2%. Use these to check your own total, not to set it. Your own ledger outranks any table.
Put it to work
Track your overhead in Clamp
All 21 categories above are pre-built in Clamp's overhead tracker with these planning ranges shown as you enter your own numbers against an annual revenue goal. Your markup multiplier falls out of the totals.
Total your overhead, add your net profit target as shares of revenue, and the markup follows from the multiplier, walked through on the same published bathroom estimate in the markup vs margin guide linked below. If you want a direct job cost to apply it to, describe a job in the free estimator.
Sources & provenance
- Clamp overhead planning defaults Clamp Research
- About Schedule C (Form 1040), Profit or Loss from Business Internal Revenue Service (official source)
- Remodelers Saw Profit Margin Gains in 2024 (Remodelers' Cost of Doing Business Study, 2026 Edition) National Association of Home Builders (research)
- Builders' Profit Margins Improved in 2023 (Cost of Doing Business Study, 2025 Edition) National Association of Home Builders (research)
- Markup & Profit: A Contractor's Guide, Revisited Michael C. Stone (book)