Independent Contractor Mileage Deduction 2026: 72.5¢, Then 76¢ From July
Multiply your business miles by the IRS rate for the date you drove them. In 2026 that is 72.5 cents through June and 76 cents from July, so a year-end total alone cannot be priced.
The assumptions
This model assumes
- Self-employed business mileage. A corporation's owner-employee is in a different posture
- You qualify to use the standard-mileage method and can substantiate the eligible miles
- 6,000 eligible business miles, allocated evenly between the two 2026 rate periods
- An illustrative scenario, not an observed contractor average
- Independent of the published hourly-rate model; it adds no hours or expenses to it
The model, step by step
If you work as an independent contractor, the IRS generally considers you self-employed, and this is the calculation that applies to you. This article illustrates the standard mileage calculation for deductible self-employed business mileage. The same IRS rate can also be used in qualifying employee reimbursement arrangements under an accountable plan.
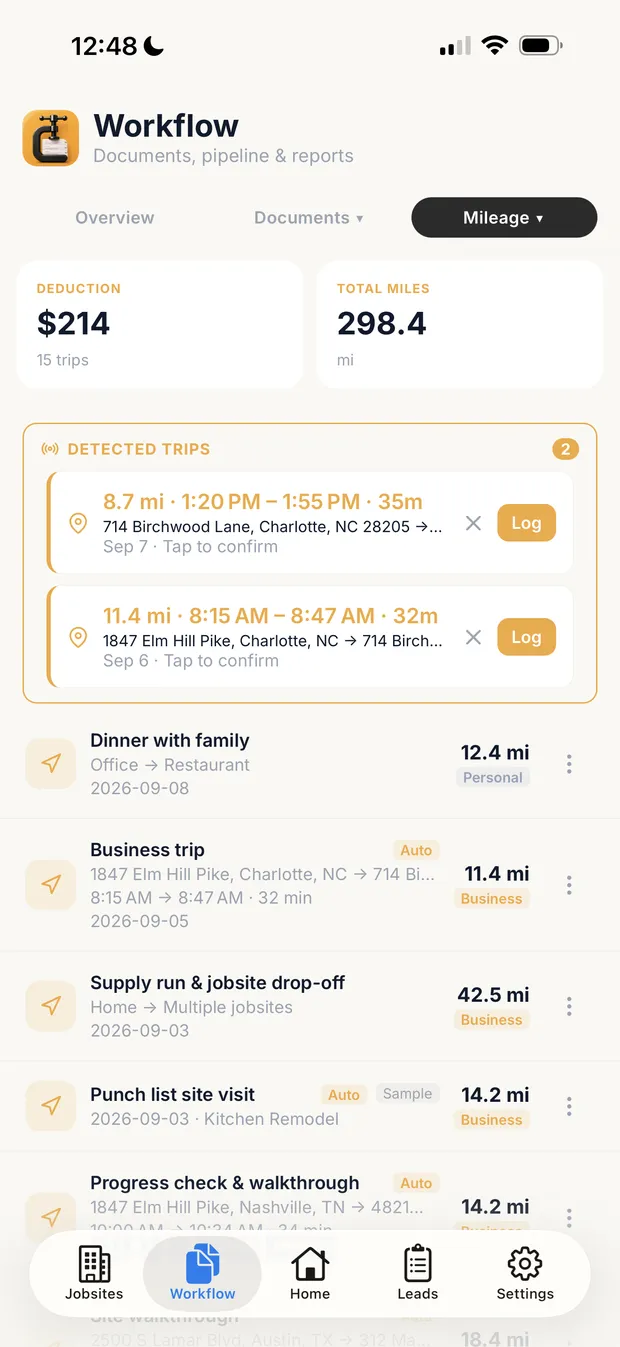
Detected, then confirmed
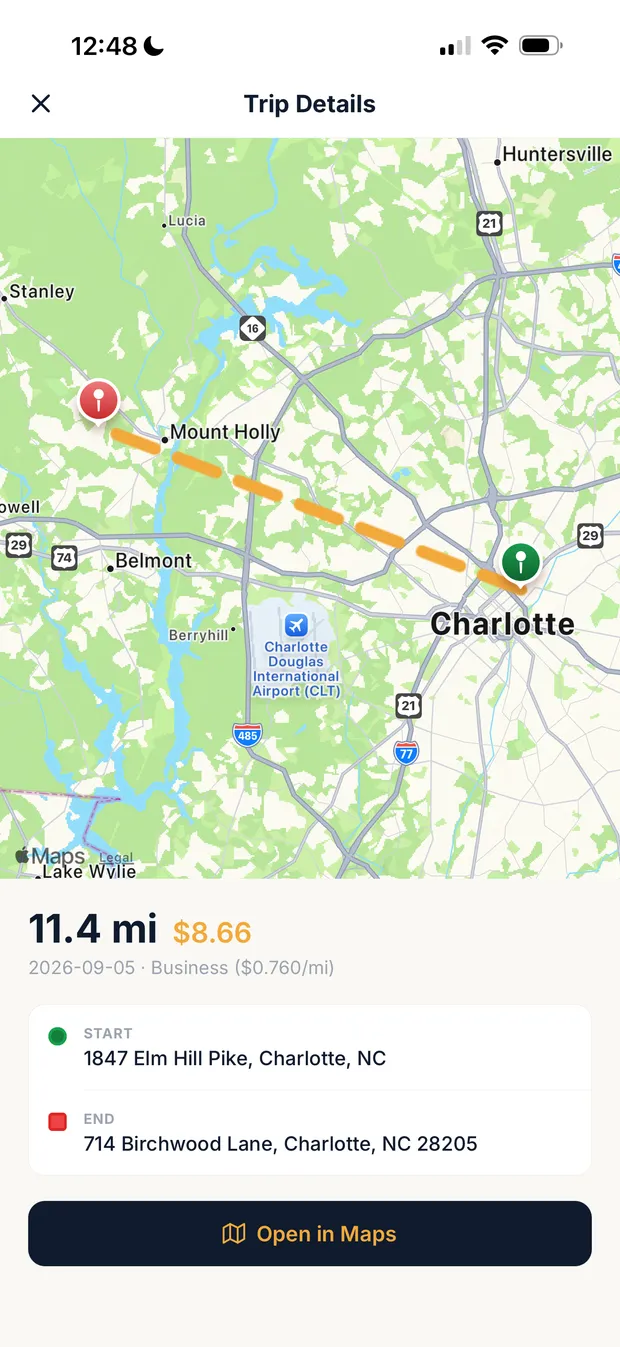
Rate by trip date
Sample data. Detected drives wait for confirmation before they count, a logged trip can sit on the job it belongs to, and each trip carries the IRS rate for its own date.
If you operate through a corporation and are an employee of it, the reporting mechanics are different. The IRS generally treats corporate officers who provide services as employees, and unreimbursed employee mileage is generally not a personal federal deduction. On officer employment status see S corporation employees, shareholders and corporate officers; on the reimbursement and unreimbursed-expense rules see Publication 463.
2026 carries two business rates. Your log has a line in the middle of it, and the halves are calculated separately.
| Period | Business | Medical and moving | Charitable |
|---|---|---|---|
| Jan 1 to Jun 30 2026 | $0.725 | $0.205 | $0.14 |
| Jul 1 to Dec 31 2026 | $0.76 | $0.235 | $0.14 |
Classify the trip before calculating its deduction.
Ordinary commuting is generally not deductible. Travel between your home and a regular workplace is ordinarily commuting unless an exception applies; distance alone does not change that result. See Publication 463.
Home-to-jobsite travel needs a separate eligibility check. A qualifying principal-place-of-business home office can make these trips deductible. Temporary-work-location exceptions can also apply without one. "Temporary" has a specific tax meaning; a remodeling job being finite does not by itself make every home-to-jobsite trip deductible. Where you have one or more regular work locations away from home, travel from home to a temporary location in the same trade or business can qualify; with no regular work location and no qualifying home office the rule is more restrictive.
Count each eligible trip segment once. In the scenario below, supplier trips and estimate visits are separate travel, not miles already counted in another row.
This article does not establish an average for contractors. It uses an explicit scenario you can replace with your own records. Your mileage will depend on geography, supplier distance, scheduling and lead volume.
| Assumed activity | Frequency | Eligible miles per trip | Annual eligible miles |
|---|---|---|---|
| Additional supplier trips | 2/week x 48 weeks | 20 | 1,920 |
| Estimate and site-assessment visits | 1/week x 48 weeks | 35 | 1,680 |
| Transfers between business locations | 2/week x 48 weeks | 25 | 2,400 |
| Total | 6,000 |
The three answers are different and they are commonly confused.
The deduction. In this eligible, substantiated, evenly split scenario, the deduction is $4,455.00. That is the amount that reduces taxable income.
The tax effect is not $4,455.00. At a hypothetical 25% federal income-tax rate, $4,455.00 x 25% = $1,113.75, as a simple income-tax illustration only. That is not a prediction of total tax savings: self-employment tax, QBI, state taxes and other interactions can change the result.
The potential deduction omitted. Suppose 1,000 otherwise eligible business miles are left out, with 500 in each rate period. Those miles represent a potential $742.50 deduction, not $742.50 of tax savings. Missing log entries do not by themselves establish that a deduction is permanently lost; whether other evidence supports the claim is a separate question.
| Eligible miles, half in each rate period | Deduction |
|---|---|
| 4,000 | $2,970.00 |
| 6,000 | $4,455.00 |
| 8,000 | $5,940.00 |
| 10,000 | $7,425.00 |
Here is an illustrative entry for a supplier trip.
| Field | Value |
|---|---|
| Vehicle | Work van A |
| Date | August 18, 2026 |
| Route | Oak Street jobsite to supplier to Oak Street jobsite |
| Business purpose | Collect tile ordered for the Oak Street bathroom |
| Eligible business miles | 20.0 |
| Applicable standard rate | $0.76 |
| Calculated mileage amount | $15.20 |
A total at year end is not a mileage record.
For each business use, keep the date, the business miles, the destination and the business purpose. Separately, retain the vehicle-level information your tax records need, including total annual mileage and, where applicable, when the vehicle began business use and its cost and basis information. The substantiation table in Publication 463 sets out both.
Why an annual total cannot be priced in 2026
| Miles driven January to June | unknown from a total |
| Miles driven July to December | unknown from a total |
| Rate applicable to each | $0.725 and $0.76 |
| Deduction computable | No |
| An annual total establishes | neither the trip-level details nor the mileage in each rate period |
The second failure is reconstructing from memory in April. Records made at or near the time of use are what the rules favour, and a weekly log qualifies. Reconstruction is not automatically disqualifying, and records destroyed beyond your control can be reconstructed, but a log built months later from calendar guesswork is weaker evidence than one kept as you went.
What it means
A trip record with the date already on it
Clamp records mileage against the job that caused it, with the date, the distance, the start and destination, and whether it was business or personal. Rates resolve by trip date, so a June trip and an August trip are valued differently. Trips detected automatically are held for your review rather than counted for you, because eligibility is your judgement and not the app's.
Pull one month of your own trips. For each, write the date, the miles, where you went and why. Split them at July 1 and apply the two rates. That figure is your deduction for one month, and the gap between it and what you would have claimed from memory is the answer to whether logging is worth it.
Questions
How much is the mileage deduction for an independent contractor?
Your business miles times the IRS rate for the date you drove them: 72.5 cents a mile through June 30, 2026, and 76 cents from July 1. 1,000 miles is $725 in the first half of the year and $760 in the second; 5,000 miles is $3,625 and $3,800; 10,000 miles is $7,250 and $7,600. It lowers your taxable income, so the tax it saves is a fraction of that figure.
Where does the mileage deduction go on my tax return?
On Schedule C (Form 1040), line 9, car and truck expenses: your business miles at the standard rate, plus business parking fees and tolls. Part IV of Schedule C asks for the vehicle's details, including its business, commuting and other miles, unless you have to file Form 4562 for it. The rest of the form, line by line, is in Schedule C deductions for remodelers.
Can independent contractors deduct mileage?
Yes. The IRS generally treats an independent contractor as self-employed, so business miles are deductible using either the standard mileage rate or actual expenses. Commuting between home and a regular place of work is personal and is not.
Is driving from home to a job site deductible?
It depends on where your regular place of work is. If your home is your principal place of business, trips from home to another work location are deductible. Trips to a temporary work location can also qualify; Publication 463 sets out when. Driving to a regular place of work is commuting.
What does a mileage log need?
For each trip: the miles, the date, the destination and the business purpose. The IRS says a log recorded at or near the time of the trip is best.
Can I switch between the standard rate and actual expenses?
For a car you own, you must choose the standard mileage rate in the first year the car is used in your business; after that you can use either method. For a leased car, choosing the standard rate means using it for the entire lease. Business parking and tolls are deductible separately under either method.
If a client reimburses my mileage, is it income?
If you adequately account to the client for the expenses, you do not report the reimbursement as income. If you do not, you report the full reimbursement as income and deduct your eligible expenses on your own return.
Sources & provenance
- Standard mileage rates Internal Revenue Service (official source)
- Announcement 2026-11, Internal Revenue Bulletin 2026-29 Internal Revenue Service (official source)
- Publication 463, Travel, Gift, and Car Expenses Internal Revenue Service (official source)
- Topic no. 510, Business use of car Internal Revenue Service (official source)
- S corporation employees, shareholders and corporate officers Internal Revenue Service (official source)
- Independent contractor (self-employed) or employee? Internal Revenue Service (official source)
- Instructions for Schedule C (Form 1040), 2025 Internal Revenue Service (official source)