1099-NEC Threshold 2026: The $2,000 Rule for Contractors Paying Subs
From 2026 you file a 1099-NEC only for a sub you paid $2,000 or more during the year, up from $600. Who gets one, what counts toward the $2,000, five subs worked, and the February 1, 2027 deadline.
The assumptions
This model assumes
- A remodeler filing as a sole proprietor, paying subs during calendar year 2026
- The subs are independent contractors doing construction work, not employees
- Each sub returned a Form W-9; no backup withholding unless stated
- Federal rules; state rules are in step 8. Not tax advice for a specific return
The model, step by step
For payments made after December 31, 2025, the federal threshold for a 1099-NEC is $2,000, up from $600. It is a total for the calendar year, per sub, and exactly $2,000 counts.
| Item | 2026 |
|---|---|
| 1099-NEC, subs and other servicesWas $600 for 2025 payments | $2,000 |
| Backup withholding startsMoves with the 1099-NEC threshold | $2,000 |
| 1099-MISC rents and other incomeRoyalties stay $10 | $2,000 |
| Attorney gross proceeds, 1099-MISCUnchanged | $600 |
| 1099-K, payment networksOver $20,000 and more than 200 transactions; cards have no minimum | $20,000 |
From 2027 the $2,000 is adjusted for inflation each year, rounded to the nearest $100. As of October 28, 2026, the IRS had not published a 2027 figure.
Go by the tax classification the sub checks on Form W-9, not the word on their truck. Ask for the W-9 before the first payment and keep it four years.
Sole proprietor
1099-NECYes, at $2,000 or more
Name and numberTheir name and SSN or EIN from the W-9
Single-member LLC owned by a person
1099-NECYes, at $2,000 or more
Name and numberThe owner's name and number, with the LLC name on the second line
Partnership, or LLC taxed as one
1099-NECYes, at $2,000 or more
Name and numberThe partnership's name and EIN
C corporation, S corporation, or LLC taxed as either
1099-NECGenerally no
ExceptionLegal fees to an attorney's corporation are still reported
Add up everything you paid one sub during 2026, across every job. Then take out what the processor reports.
Counts
Paid byCheck, cash, ACH and bank transfers, including Zelle
IncludesParts and materials the sub supplies as part of the work, which the IRS counts with the service
Doesn't count
Paid byCredit or debit card, or a payment network such as PayPal or Venmo for business
WhyThe card company or network reports it on Form 1099-K instead
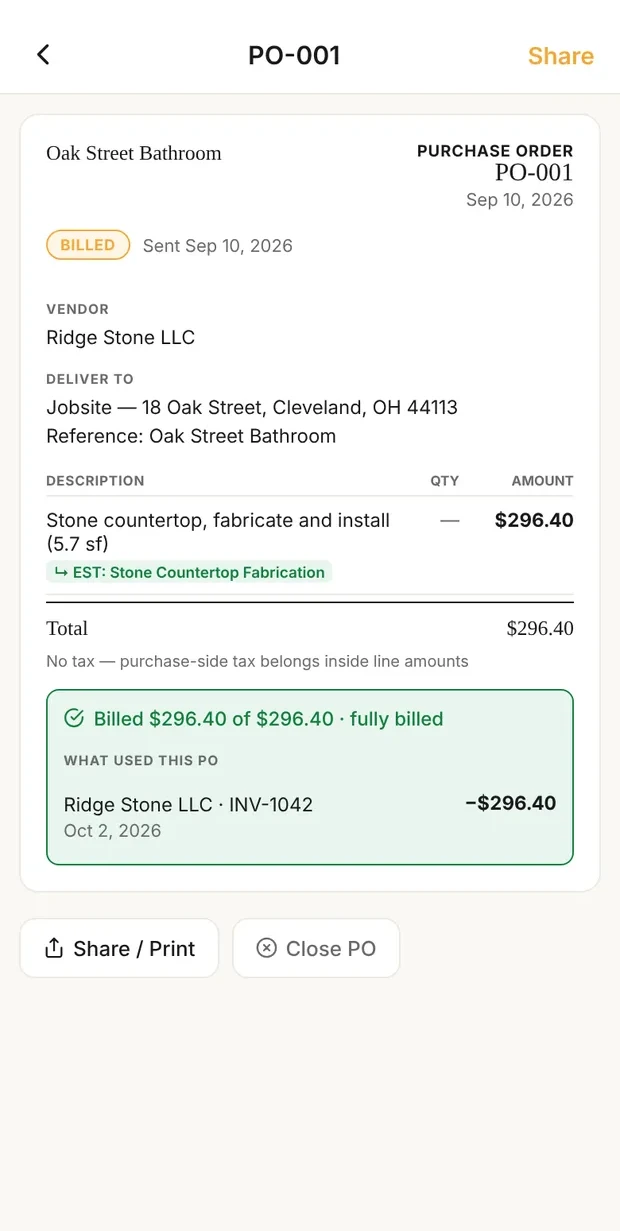
The sub's order
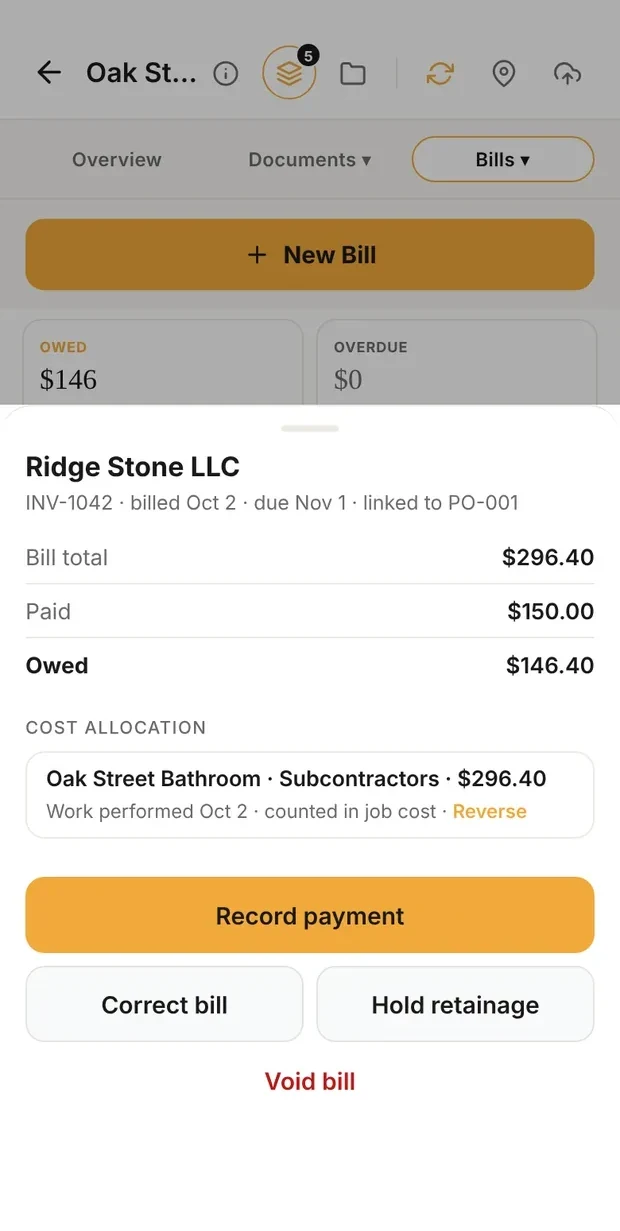
The bill and what's paid
A countertop sub's purchase order and bill in Clamp: the bill uses the order up, and the $150 payment leaves $146.40 owed. Demo data on the published 5x8 bathroom.
A remodeler pays five subs in 2026, $30,100 in all.
| Sub | Counts | 1099-NEC |
|---|---|---|
| A: sole proprietor$1,950 by check, under $2,000 | $1,950 | No |
| B: single-member LLCBy check; owner's name and number | $2,050 | $2,050 |
| C: S corporation$18,000 by check; corporation | $0 | No |
| D: sole proprietor$6,000 by credit card; on a 1099-K | $0 | No |
| E: sole proprietor$1,200 check + $900 Zelle | $2,100 | $2,100 |
Under the old $600 rule, A would have needed one too: three forms and $6,100. The payment method decides E. If the $900 had gone by card or PayPal for business, only the $1,200 check would count, and E would get no form.
If a sub won't give you a taxpayer identification number, you still report, and you withhold. Once the year's payments to that sub reach $2,000, withhold 24% from the payment that gets there and from every payment after, and send it to the IRS. If you had to file a 1099 for this sub last year, start with the first payment. The example below is a sub who needed no form for 2025.
File the IRS copy and give the sub their copy by Monday, February 1, 2027. January 31 is a Sunday, so the due date moves to the next business day. There is no automatic extension.
10 or more returns
RuleE-file if you file 10 or more information returns in total, Forms W-2 included
WhereIRIS, the IRS's free portal, or an e-file service
Fewer than 10
RulePaper is still allowed
TipOrder the scannable red IRS forms; printed copies of the web form aren't accepted
A missing form can be penalized twice: once for the IRS copy and once for the sub's copy. Each copy is penalized separately.
| When corrected | Per form |
|---|---|
| Within 30 days | $60 |
| By August 1, 2027 | $130 |
| After August 1, or never | $340 |
| Intentional disregardOr 10% of the amount, if more; no annual cap | $690 |
Filing a 1099 and deducting what you paid the sub are separate questions. The deduction rests on the bill and proof of payment, as with any business expense; the missing form brings the penalty.
States set their own rules, and some kept the old numbers or require you to file with them directly.
Wisconsin
Threshold$600 for 1099s filed with the state, per guidance dated January 30, 2026; Wisconsin had not adopted the federal change
New Jersey
Threshold$1,000 in its withholding instructions dated September 2025, or any payment with New Jersey tax withheld
Pennsylvania
ThresholdIts guidance, updated August 2026, still says $600; it hasn't said whether that is deliberate
AlsoFile with the state; 3.07% withholding when a nonresident sub who is an individual or a single-member LLC is paid $5,000 or more in the year for Pennsylvania work
California
Threshold$2,000
Also7% withholding on payments over $1,500 a year to a nonresident sub for California work
Massachusetts
FilingSend 1099-NECs to the Department of Revenue directly, even through the combined federal and state program
What it means
Each sub payment, recorded with how you paid
In Clamp each sub is a vendor, and every bill and payment sits on the job it belongs to, with how you paid it: check, card, ACH, cash or other. In January you total each sub from records you kept as you went, not a bank statement.
Pull every sub you paid this year and write two numbers next to each name: what you paid by check, cash or transfer, and what you paid by card. The first column decides who gets a form.
Questions
What is the 1099-NEC threshold for 2026?
$2,000. For payments made after December 31, 2025, you file a 1099-NEC for a sub you paid $2,000 or more during the year for services. It was $600 through 2025, and it may be adjusted for inflation starting in 2027.
Do I send a 1099-NEC to an LLC?
It depends on how the LLC is taxed, which its Form W-9 tells you. A single-member LLC owned by a person, or an LLC taxed as a partnership, gets one; a single-member LLC's form goes under the owner's name and tax ID, with the LLC name on the second line. An LLC taxed as a C or S corporation, or owned by one, generally does not.
Do payments by credit card or Zelle count toward the $2,000?
Card payments and payments through a payment network such as PayPal for business are reported on Form 1099-K, so they don't count toward your 1099-NEC. Zelle moves money between bank accounts and doesn't issue a 1099-K. No IRS page names Zelle, so this guide counts Zelle payments like a check.
When are 1099-NEC forms due for 2026 payments?
Monday, February 1, 2027, for both the copy you file with the IRS and the copy you give the sub. January 31, 2027 is a Sunday, so the due date moves to the next business day.
What if a sub won't give me a W-9?
You still have to report. Once the year's payments to that sub reach $2,000, withhold 24% backup withholding from the payment that gets there and every payment after, and send it to the IRS. If you had to file a 1099 for that sub last year, withhold from the first payment.
Sources & provenance
- Instructions for Forms 1099-MISC and 1099-NEC (Rev. December 2026) Internal Revenue Service (official source)
- 26 U.S.C. 6041, Information at source Office of the Law Revision Counsel, U.S. House of Representatives (official source)
- Publication 1099, General Instructions for Certain Information Returns guide (2026) Internal Revenue Service (official source)
- Proposed regulations REG-113229-25 on information reporting thresholds, Internal Revenue Bulletin 2026-19 Internal Revenue Service (official source)
- Instructions for the Requester of Form W-9 (Rev. March 2024) Internal Revenue Service (official source)
- Forms and associated taxes for independent contractors Internal Revenue Service (official source)
- Publication 15, Employer's Tax Guide (2026) Internal Revenue Service (official source)
- Topic no. 801, Who must file information returns electronically Internal Revenue Service (official source)
- E-file information returns with IRIS Internal Revenue Service (official source)
- Rev. Proc. 2025-32, Internal Revenue Bulletin 2025-45 Internal Revenue Service (official source)
- Instructions for Form 1099-K (Rev. December 2026) Internal Revenue Service (official source)
- Topic no. 762, Independent contractor vs. employee Internal Revenue Service (official source)
- What kind of records should I keep Internal Revenue Service (official source)
- Does Zelle report how much money I receive to the IRS? Zelle (Early Warning Services) (official source)
- Tax practitioner questions and answers, fall 2025 Wisconsin Department of Revenue (official source)
- NJ-WT, New Jersey Income Tax Withholding Instructions (September 2025) New Jersey Division of Taxation (official source)
- What is the minimum amount of nonemployee compensation that must be reported? (answer 2904) Pennsylvania Department of Revenue (official source)
- Nonresident withholding Pennsylvania Department of Revenue (official source)
- Guide to information returns filed with California California Franchise Tax Board (official source)
- 2026 Instructions for Form 592 California Franchise Tax Board (official source)
- Form 1099 filing requirements Massachusetts Department of Revenue (official source)