W-9 for Subcontractors (2026): Get It Before the First Check, or Withhold 24%
What the W-9 tells you, who gets a 1099-NEC at the new $2,000 threshold, and a drywall sub with no W-9 worked: $2,016 withheld and the penalties you can avoid.
The assumptions
This model assumes
- A remodeler paying subcontractors in 2026
- The sub is a US sole proprietor, not a corporation
- Paid by check, not by card or a payment network
- No taxpayer ID on file unless the example says otherwise
- Federal rules; states may have their own reporting. Not tax advice for a specific situation
The model, step by step
The W-9 is the form a sub fills out so you have their legal name, tax classification and taxpayer identification number (TIN). You don't file it; you keep it and use it for the 1099-NEC.
When
AskWhen you hire the sub, before the first check. The IRS counts your first request from when the relationship starts.
VersionThe current form is Rev. March 2024. Use it for every new sub.
Where it goes
Keep itIn your files, not with the IRS. The IRS says to keep it four years.
ElectronicAn e-signed W-9 is fine if your system meets the IRS rules for electronic forms.
Check these before you file the form away. A wrong name or number is what triggers penalties later.
| Line | What to check |
|---|---|
| 1For a single-member LLC, the owner's name goes here | Legal name |
| 2The LLC or trade name, if different | Business name |
| 3aDecides whether the sub gets a 1099-NEC | Tax classification |
| 4Exempt payee code 5 means a corporation | Exemptions |
| Part ISSN or EIN; nine digits, matching line 1 | TIN |
| Part IIAsk for it; for ordinary sub pay the IRS requires a correct TIN | Signature |
The classification box decides it. File a 1099-NEC for each sub you pay $2,000 or more in 2026, up from $600.
| Sub | 1099-NEC? |
|---|---|
| Sole proprietorUnder the person's name and SSN or EIN | Yes |
| Single-member LLCUnder the owner's name and number | Yes |
| LLC taxed as partnershipUnder the LLC's name and EIN | Yes |
| C or S corporationIncluding an LLC taxed as one; law firms still get one | No |
Payments by credit card or through a qualifying payment network are reported on Form 1099-K by the processor, not by you. An app that just moves money from your bank isn't automatically one.
A remodeler hires a drywall sub, a sole proprietor, and pays $8,400 in 2026 in three checks of $2,800. The sub never gives a TIN.
With no TIN, you withhold 24% starting with the payment that brings the sub's year to $2,000, on that whole payment and every one after. Here the first check alone passes $2,000, so all three are withheld. The sub nets $6,384, or $7,728 if they hand over the W-9 before check two.
The $2,000 wait doesn't apply if you had to file a 1099 for this sub, or withhold from them, in 2025. Then withholding starts with the first dollar.
Backup withholding isn't payroll. It has its own form and deposits.
Form 945
ReportAll backup withholding for the year on Form 945, separate from Form 941
PayIf the year's total is under $2,500, like the $2,016 here, you can pay it with the return
The 1099-NEC
Pay$8,400, the gross pay, not the net checks
Withheld$2,016 federal income tax withheld
If you didn't withhold
You owe itA payer who should have withheld can be liable for the amount not collected
Late W-9A W-9 that comes in later stops withholding on future checks. It doesn't cancel what you should have withheld from earlier ones.
If a sub never gives a TIN, the IRS can waive the penalty when you show reasonable cause. For a missing TIN, that means asking on a set schedule and keeping proof.
| Request | By |
|---|---|
| InitialA W-9 with your first contract or onboarding packet | Start of work |
| First annualJanuary 31 if the work started in December | Dec 31, same year |
| Second annualOnly if the TIN is still missing | Dec 31, next year |
By mail, send a letter, a W-9 and a return envelope. By phone, keep a record of the call. Save it all with the sub's file.
The penalty is per form, for 1099s filed in 2027 for 2026 payments, and it depends on how fast you fix it.
| Fixed | Per form |
|---|---|
| Within 30 days | $60 |
| By August 1, 2027 | $130 |
| After that, or never | $340 |
| Intentional disregardThe greater of $690 or 10% of the $8,400 | $840 |
A separate penalty can apply to the sub's copy if it's also late or wrong. Small businesses, with $5 million or less in receipts, have yearly caps starting at $244,500.
Two last habits close the loop.
IRS TIN Matching
WhatChecks a sub's name and TIN against IRS records before you file
HowFree through IRS e-Services: up to 25 at once, or 100,000 in a bulk file within 24 hours
WhoPayers who filed qualifying information returns in one of the two prior years
When you're the sub
Send yoursAttach your W-9 and insurance certificate to proposals, so the general contractor never has to ask
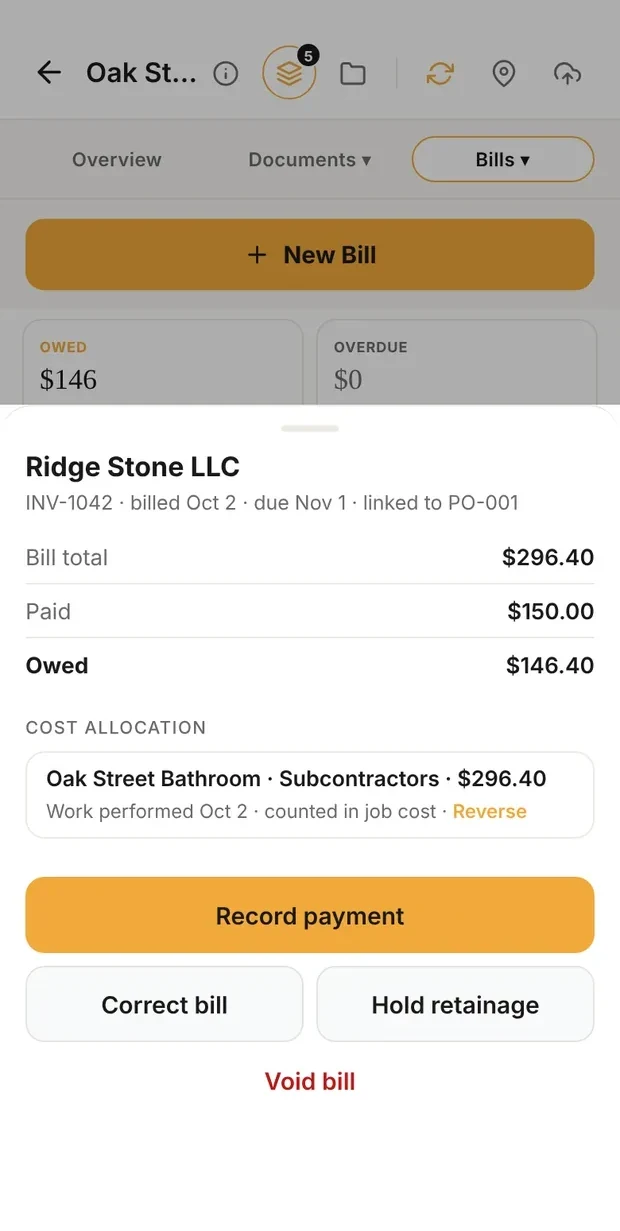
Each sub's bill and payment
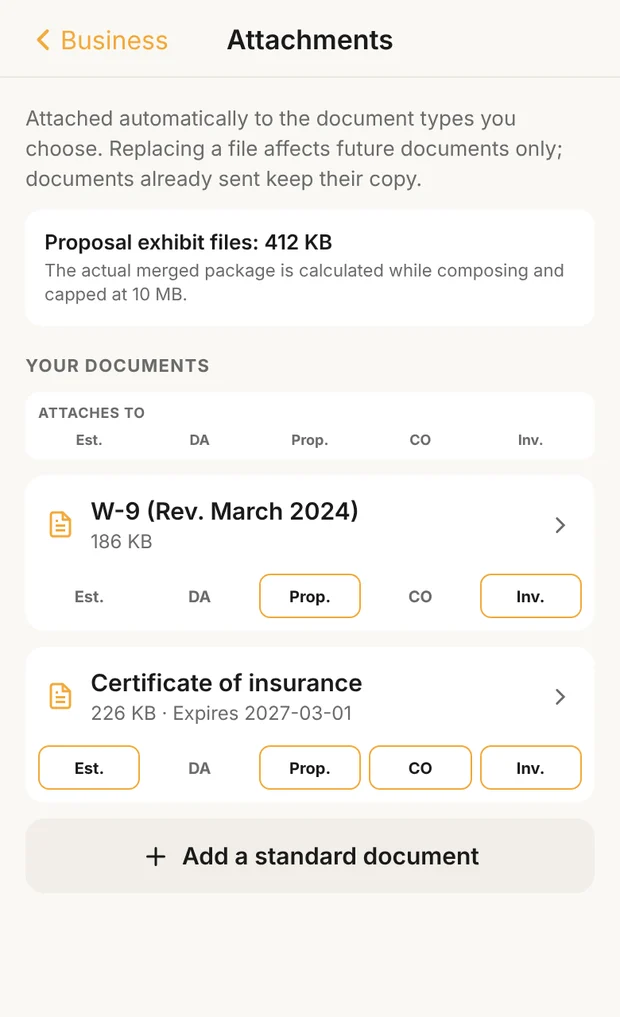
Your W-9 goes with the proposal
In Clamp, a sub's bill with what's paid and owed, and the Attachments setting where your own W-9 goes out with every proposal and invoice. Demo data.
What it means
The year's total for each sub
Clamp records each sub's bills and every payment against them, with the date and the method, so January's 1099 numbers come from records you already keep. Clamp doesn't store subs' W-9s or file 1099s. When you're the sub, your own W-9 and insurance certificate attach to every proposal you send.
Before January, pull every sub you paid this year, add up each one's checks, and confirm you have a W-9 for everyone at $2,000 or more. Missing ones get a written request now, before the February 1 deadline.
Questions
Do I need a W-9 from my subcontractor?
Yes. The W-9 gives you the sub's legal name, tax classification and taxpayer ID, which you need to file a 1099-NEC once you pay them $2,000 or more in 2026. Ask for it when the work starts, and keep it; it isn't sent to the IRS.
What if a subcontractor won't fill out a W-9?
Ask in writing when the work starts, again by December 31, and again by December 31 the next year. With no taxpayer ID, withhold 24% from their payments once the year's total reaches $2,000, and report it on Form 945.
Do LLCs need a 1099?
Most do. A single-member LLC is reported under the owner's name and number, and an LLC taxed as a partnership gets one too. An LLC taxed as a C or S corporation generally doesn't, unless it's a law firm.
Do I send the W-9 to the IRS?
No. You keep it. The IRS says to keep it in your files for four years.
What is the 1099 threshold for 2026?
$2,000 per sub for payments made in 2026, up from $600. File the 1099-NEC by February 1, 2027, because January 31 is a Sunday.
Sources & provenance
- Form W-9, Request for Taxpayer Identification Number and Certification (Rev. March 2024) Internal Revenue Service (official source)
- Instructions for the Requester of Form W-9 (Rev. March 2024) Internal Revenue Service (official source)
- Forms and associated taxes for independent contractors Internal Revenue Service (official source)
- 26 U.S. Code 6041, information at source Office of the Law Revision Counsel (official source)
- 26 U.S. Code 3406, backup withholding Office of the Law Revision Counsel (official source)
- REG-113229-25, backup withholding and the $2,000 threshold (proposed) Federal Register (official source)
- Publication 15 (2026), Employer's Tax Guide Internal Revenue Service (official source)
- Publication 1099 (2026), General Instructions for Certain Information Returns Internal Revenue Service (official source)
- Instructions for Forms 1099-MISC and 1099-NEC Internal Revenue Service (official source)
- Publication 1586 (Rev. 8-2026), Reasonable Cause Regulations and Requirements for Missing and Incorrect Name/TINs Internal Revenue Service (official source)
- Publication 1281 (Rev. 12-2023), Backup Withholding for Missing and Incorrect Name/TIN(s) Internal Revenue Service (official source)
- Rev. Proc. 2025-32, Internal Revenue Bulletin 2025-45 Internal Revenue Service (official source)
- Instructions for Form 945 Internal Revenue Service (official source)
- Taxpayer Identification Number (TIN) Matching tools Internal Revenue Service (official source)