Quarterly Estimated Taxes 2026 for Contractors: Due Dates, Safe Harbor and the Penalty, Worked
The four 2026 due dates, the safe harbor that sets the payment, and a $140,000 remodeler worked from profit to $7,000 a quarter, with what skipping the payments costs.
The assumptions
This model assumes
- A remodeler filing Schedule C as a sole proprietor, calendar year
- $140,000 of net profit in 2026, no other income, no withholding
- Single filer, standard deduction, under 65
- $28,000 of total tax for 2025, with 2025 AGI under $150,000
- Federal rules; states in step 7. Not tax advice for a specific return
The model, step by step
Estimated tax is paid four times a year, but the periods aren't equal quarters. The second payment covers two months; the third covers three.
| Income earned | Due |
|---|---|
| Jan 1 to Mar 31First payment | April 15, 2026 |
| Apr 1 to May 31Two months | June 15, 2026 |
| Jun 1 to Aug 31Three months | September 15, 2026 |
| Sep 1 to Dec 31Skip it if you file and pay in full by February 1, 2027 | January 15, 2027 |
You generally have to pay estimates when both are true: you expect to owe at least $1,000 after withholding and credits, and your withholding and credits won't reach the safe harbor. Pay the safe harbor on time and there's no penalty, even if you owe more in April.
| Test | Amount |
|---|---|
| This yearYou don't know it until the year ends | 90% of 2026 tax |
| Last yearKnown today; your 2025 return must cover 12 months | 100% of 2025 tax |
| Last year, AGI over $150,000$75,000 if married filing separately | 110% of 2025 tax |
If you owed no tax for 2025, were a U.S. citizen or resident all year, and 2025 was a full 12 months, you don't need to pay 2026 estimates.
A remodeler filing Schedule C, single, with $140,000 of net profit in 2026, no other income and the standard deduction.
| Line | Amount |
|---|---|
| Self-employment tax$140,000 x 92.35% x 15.3% | $19,781.37 |
| Half of it, deductedAGI is $130,109.31 | $9,890.69 |
| Standard deductionSingle, 2026 | $16,100 |
| Qualified business income deductionCapped at 20% of taxable income, not 20% of business income | $22,801.86 |
| Taxable incomeIn the 22% bracket | $91,207.45 |
| Income tax$1,240 + $4,560 + 22% of $40,807.45 | $14,777.64 |
This remodeler owed $28,000 for 2025, with AGI under $150,000. That's less than 90% of 2026's tax, so last year's number sets the payments.
Paying $28,000 covers the penalty, not the tax. The other $6,559.01 is due with the return by April 15, 2027. Set it aside as the year goes, or it lands on top of the first 2027 payment.
The penalty is the IRS underpayment rate, charged per day on each late installment. It isn't compounded, and it isn't the 0.5% a month late-payment penalty. Paying nothing until April 15, 2027:
| Missed payment | Penalty |
|---|---|
| April 15, 202676 days at 6%, 289 days at 7% | $475.42 |
| June 15, 202615 days at 6%, 289 days at 7% | $405.23 |
| September 15, 2026212 days at 7% | $284.60 |
| January 15, 202790 days at 7% | $120.82 |
A catch-up payment stops the penalty from growing, but doesn't erase what built up on the earlier dates.
Remodeling income is rarely even. Two rules help when it isn't.
The annualized income method
HowEach payment is figured from income actually earned through March 31, May 31, August 31 and December 31
HelpsA slow winter means a smaller April payment, with larger payments after the busy months
CostFile Form 2210 with Schedule AI, and use it for every payment that year
S corporation owners
OptionRaise federal withholding on your own W-2 pay with a new Form W-4
Why it worksWithholding counts as paid evenly on all four due dates, even if it's withheld in December
SoA large December withholding can cover short April, June and September payments; a late estimate can't
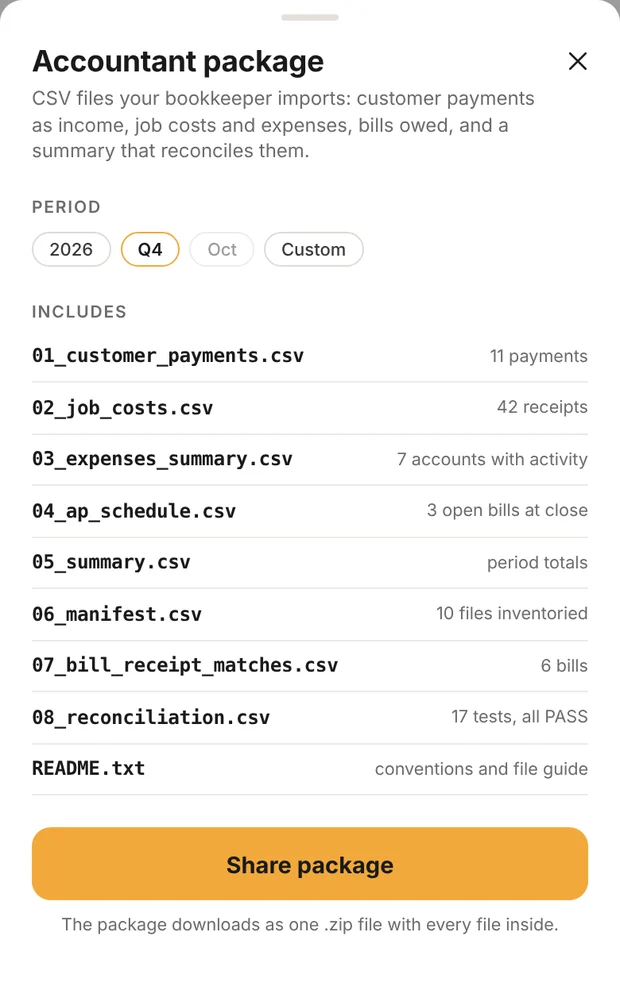
Q4 2026 for the preparer
Clamp's accountant package set to Q4 2026: October through December's customer payments and receipts, with a summary of payments received and expenses, ready before the January 15 payment. Demo data.
Most states with an income tax use the same four dates. The thresholds and splits differ.
California
Split30% April, 40% June, nothing in September, 30% January
Threshold$500 owed after withholding
High income110% of last year above $150,000 AGI; no prior-year option at $1 million
New York
Threshold$300 of state, New York City or Yonkers tax
High income110% of last year above $150,000 AGI
New Jersey
ThresholdMore than $400 owed
Safe harbor80% of this year's tax, or 100% of last year's
Pennsylvania
ThresholdMore than $14,000 of income not subject to withholding, about $430 of tax
Illinois
ThresholdMore than $1,000 owed
Texas and Florida
Personal income taxNone, so no state estimates; federal estimates still apply
Pay each estimate online and keep the confirmation.
Use
IRS Direct PayFree, from a bank account, no sign-up
IRS Online AccountSchedule payments and see what's been applied to 2026
Card or checkA card has a processor fee; a check goes with the 1040-ES voucher
EFTPS is ending for individuals
AlreadyNew individual enrollments ended October 17, 2025
NextIndividuals move off EFTPS in late 2026; no exact date has been set
DoSwitch to Direct Pay or your Online Account before January 15, 2027
What it means
The numbers your estimate starts from
Clamp records every customer payment and every receipt on the job. Export a quarter, like Q4 2026, or any date range, and the summary shows payments received and expenses for it, the starting point your preparer needs. Clamp doesn't figure your tax; your preparer does, from those records.
Put the four dates in your calendar now: January 15, 2027 is next. Before each one, check what you've collected and spent so far this year. If the year is running well ahead of last, the prior-year payment still protects you, but the April balance grows.
Questions
When are quarterly estimated taxes due for 2026?
April 15, June 15 and September 15, 2026, and January 15, 2027. You can skip the January payment if you file your 2026 return and pay the full balance by February 1, 2027.
How much should a contractor pay in estimated taxes?
Enough to reach the smaller of 90% of this year's tax or 100% of last year's tax, in four equal payments. It's 110% of last year's tax if last year's AGI was over $150,000. Last year's tax is the number you already know.
What is the estimated tax penalty rate for 2026?
The IRS underpayment rate: 7% for January to March, 6% for April to June, and 7% for the rest of 2026. It's charged per day on each late installment and isn't compounded.
Do I have to pay estimated taxes if my income is seasonal?
Yes, but you can pay less early in the year. The annualized income method on Form 2210 Schedule AI figures each payment from what you actually earned through March 31, May 31 and August 31.
Is EFTPS still available for estimated tax payments?
Not for new individual users. New individual enrollments ended October 17, 2025, and individuals are being moved off EFTPS in late 2026. Use IRS Direct Pay or your IRS Online Account.
Sources & provenance
- Form 1040-ES (2026), Estimated Tax for Individuals Internal Revenue Service (official source)
- Publication 505 (2026), Tax Withholding and Estimated Tax Internal Revenue Service (official source)
- Estimated tax FAQ: individuals Internal Revenue Service (official source)
- Estimated taxes Internal Revenue Service (official source)
- 26 U.S. Code 6654, failure by individual to pay estimated income tax Office of the Law Revision Counsel (official source)
- Instructions for Form 2210 (2025) Internal Revenue Service (official source)
- Internal Revenue Manual 20.1.3, Estimated Tax Penalties Internal Revenue Service (official source)
- 26 U.S. Code 6621 and 6622, interest rates and compounding Office of the Law Revision Counsel (official source)
- Quarterly interest rates Internal Revenue Service (official source)
- IR-2026-98, interest rates remain the same for the fourth quarter of 2026 Internal Revenue Service (official source)
- Rev. Proc. 2025-32, Internal Revenue Bulletin 2025-45 Internal Revenue Service (official source)
- Topic 554, Self-employment tax Internal Revenue Service (official source)
- Self-employment tax (Social Security and Medicare taxes) Internal Revenue Service (official source)
- Topic 751, Social Security and Medicare withholding rates Internal Revenue Service (official source)
- Instructions for Form 8995 (2025) Internal Revenue Service (official source)
- Questions and answers about Executive Order 14247 (FS-2026-02) Internal Revenue Service (official source)
- 2026 Form 540-ES instructions California Franchise Tax Board (official source)
- IT-2105-I (2026), instructions for estimated income tax New York State Department of Taxation and Finance (official source)
- NJ-1040-ES instructions (2026) New Jersey Division of Taxation (official source)
- REV-413(I), instructions for estimating PA personal income tax (2026) Pennsylvania Department of Revenue (official source)
- Publication 105, Illinois estimated payments Illinois Department of Revenue (official source)